
Customer Acquisition Cost: How to Calculate CAC and What to Include
Table of Contents
Customer acquisition cost is your total sales and marketing spend divided by the number of new customers that spend produced. Spend $180,000 in a quarter, sign 60 new customers, and your CAC is $3,000.
The arithmetic is not the hard part. The hard part is deciding what belongs in the numerator, and most teams decide it too narrowly, which is why the CAC on the board slide is often half the CAC the business is actually paying. This piece covers what to include, three ways to run the same period, and why payback period matters more than the ratio everyone quotes.
What is Customer Acquisition Cost?
Customer acquisition cost is the average amount a business spends to win one new customer over a defined period.
CAC = Total sales and marketing costs ÷ New customers acquired
Both halves need a fixed window — a quarter, a year — and both halves must describe the same window. The metric exists to answer one question: can you afford to keep buying customers at this price? Everything else it gets used for, from channel budgeting to board reporting, is downstream of that.
What Counts as an Acquisition Cost, and What Doesn't
This is where CAC calculations diverge, and it is worth being strict.
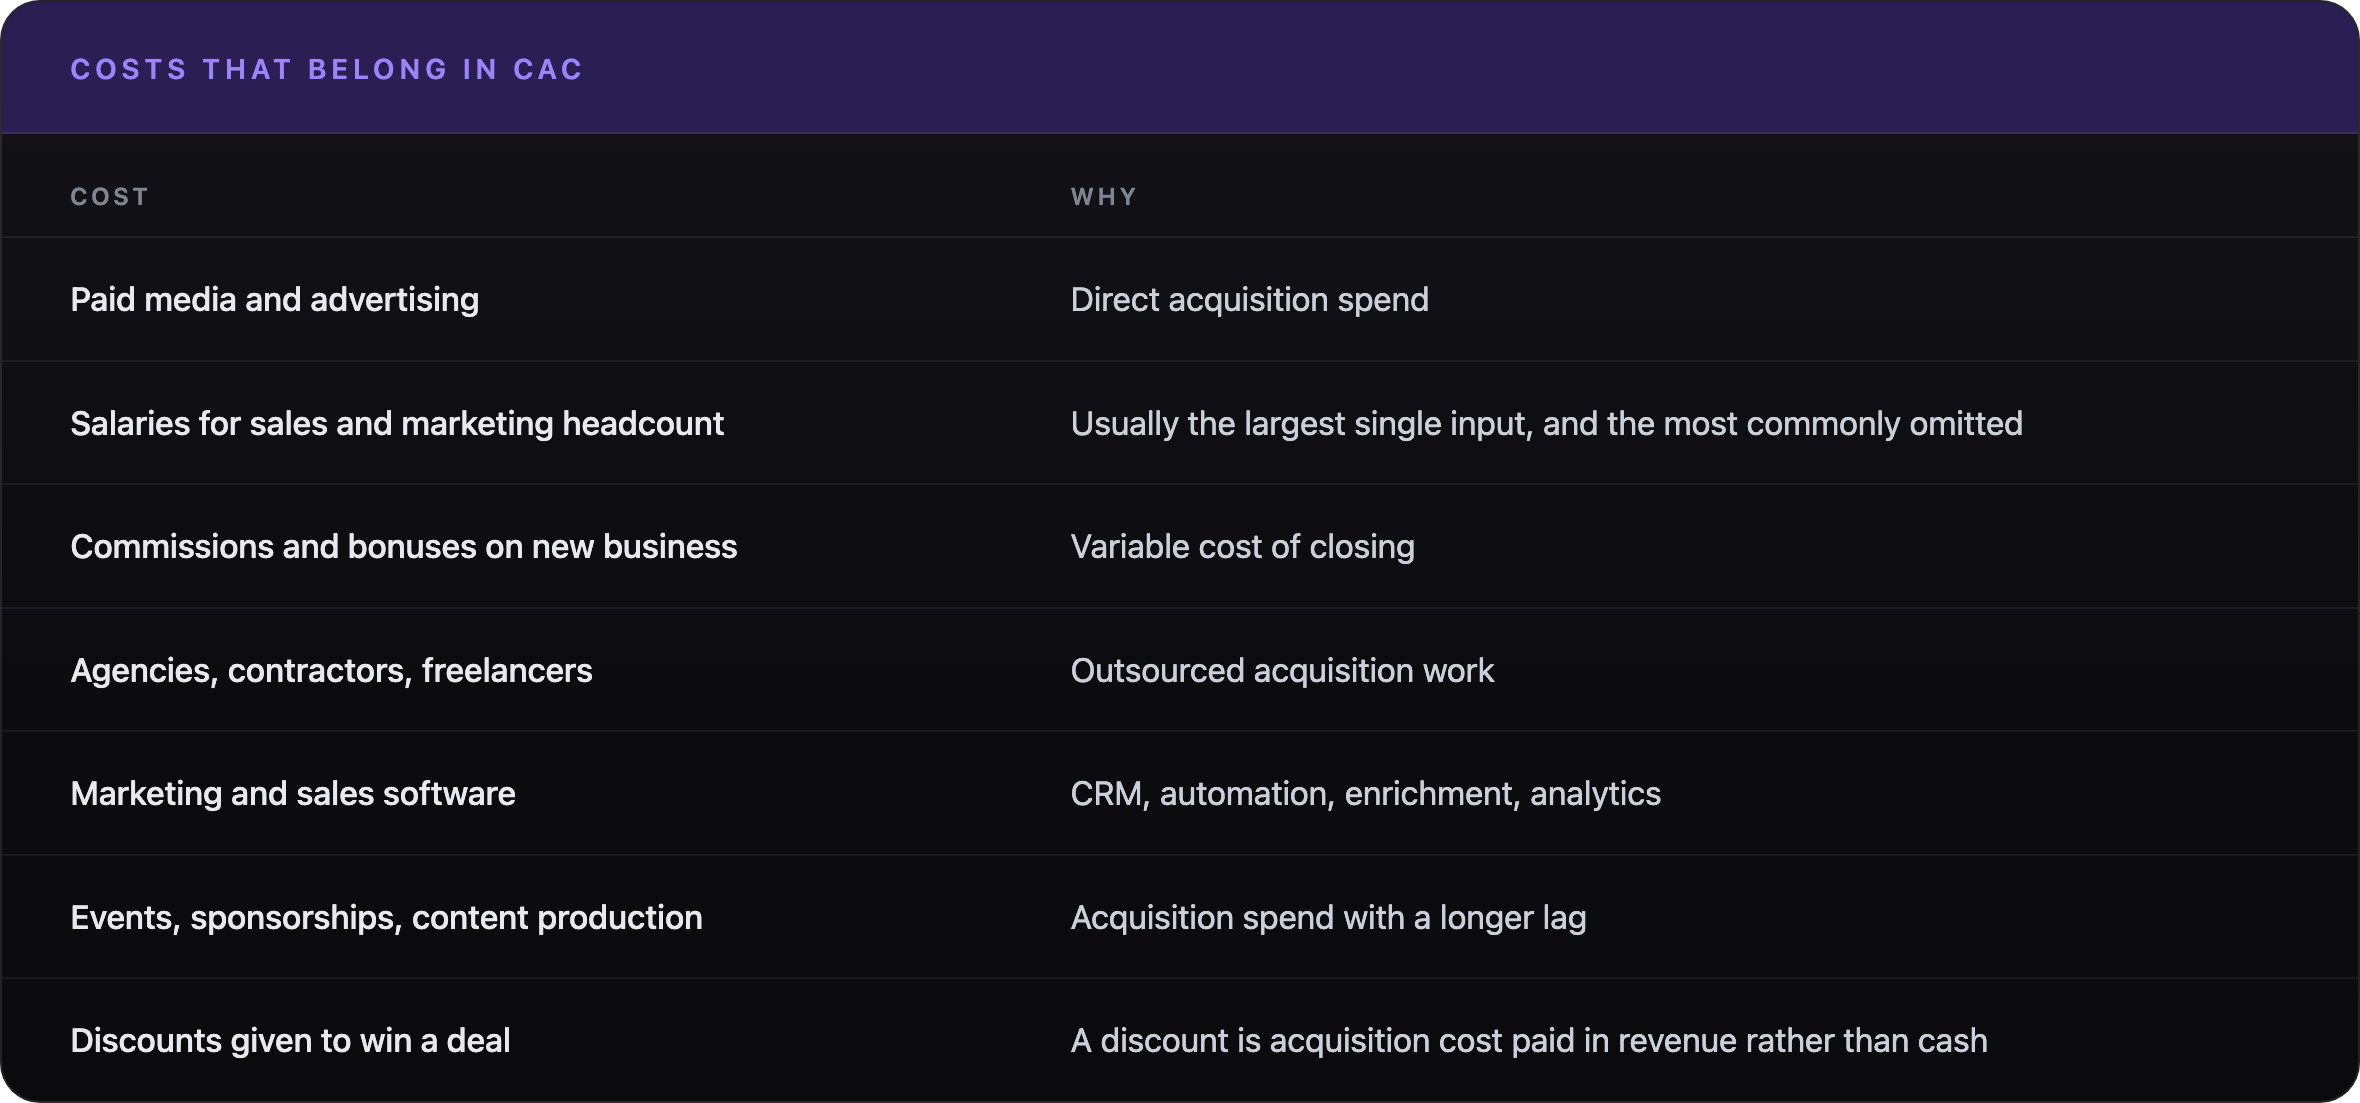
Costs to Include in CAC
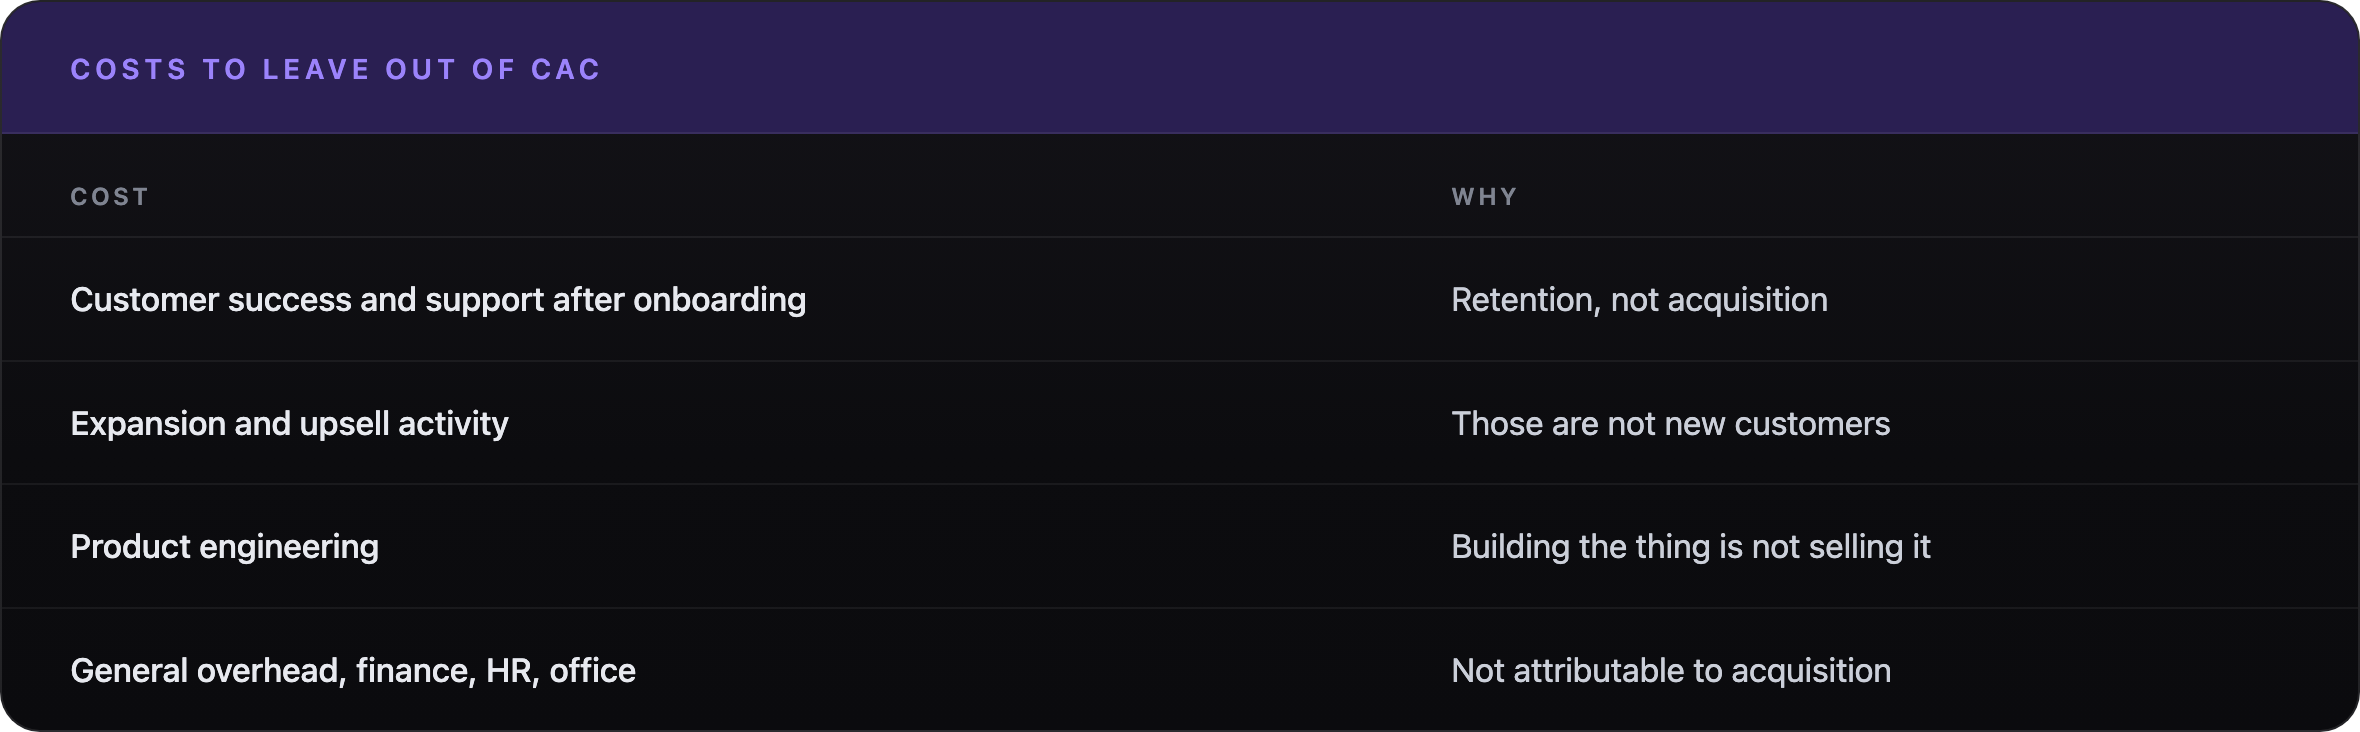
Costs to Exclude from CAC
The Ones That Cause Arguments
Four costs sit on the line, and the answer is the same for all of them.
Founder and Executive Selling Time
If a founder spends half their week in sales calls, half a founder salary is acquisition cost. Leaving it out is the single most common reason early-stage CAC looks impossibly good.
Brand and PR
Spend intended to make future selling easier is still acquisition spend. It has a longer lag, which argues for measuring it over a longer window, not for excluding it.
Partner and Affiliate Commissions
If the commission is paid for a new customer, it is acquisition cost, whatever line it sits on in the P&L.
Free-Trial Infrastructure
The compute and support consumed by people who never convert is a cost of acquiring the ones who do.
The test: if you stopped trying to acquire new customers tomorrow, would this cost fall? If yes, it belongs in CAC. Apply it to anything not listed above and you will get a defensible answer.
How to Calculate CAC Three Ways on The Same Numbers
The word "CAC" is used for at least three different figures. The gap between them is not academic, it is usually the difference between a business that looks efficient and one that doesn't.
Take One Quarter:
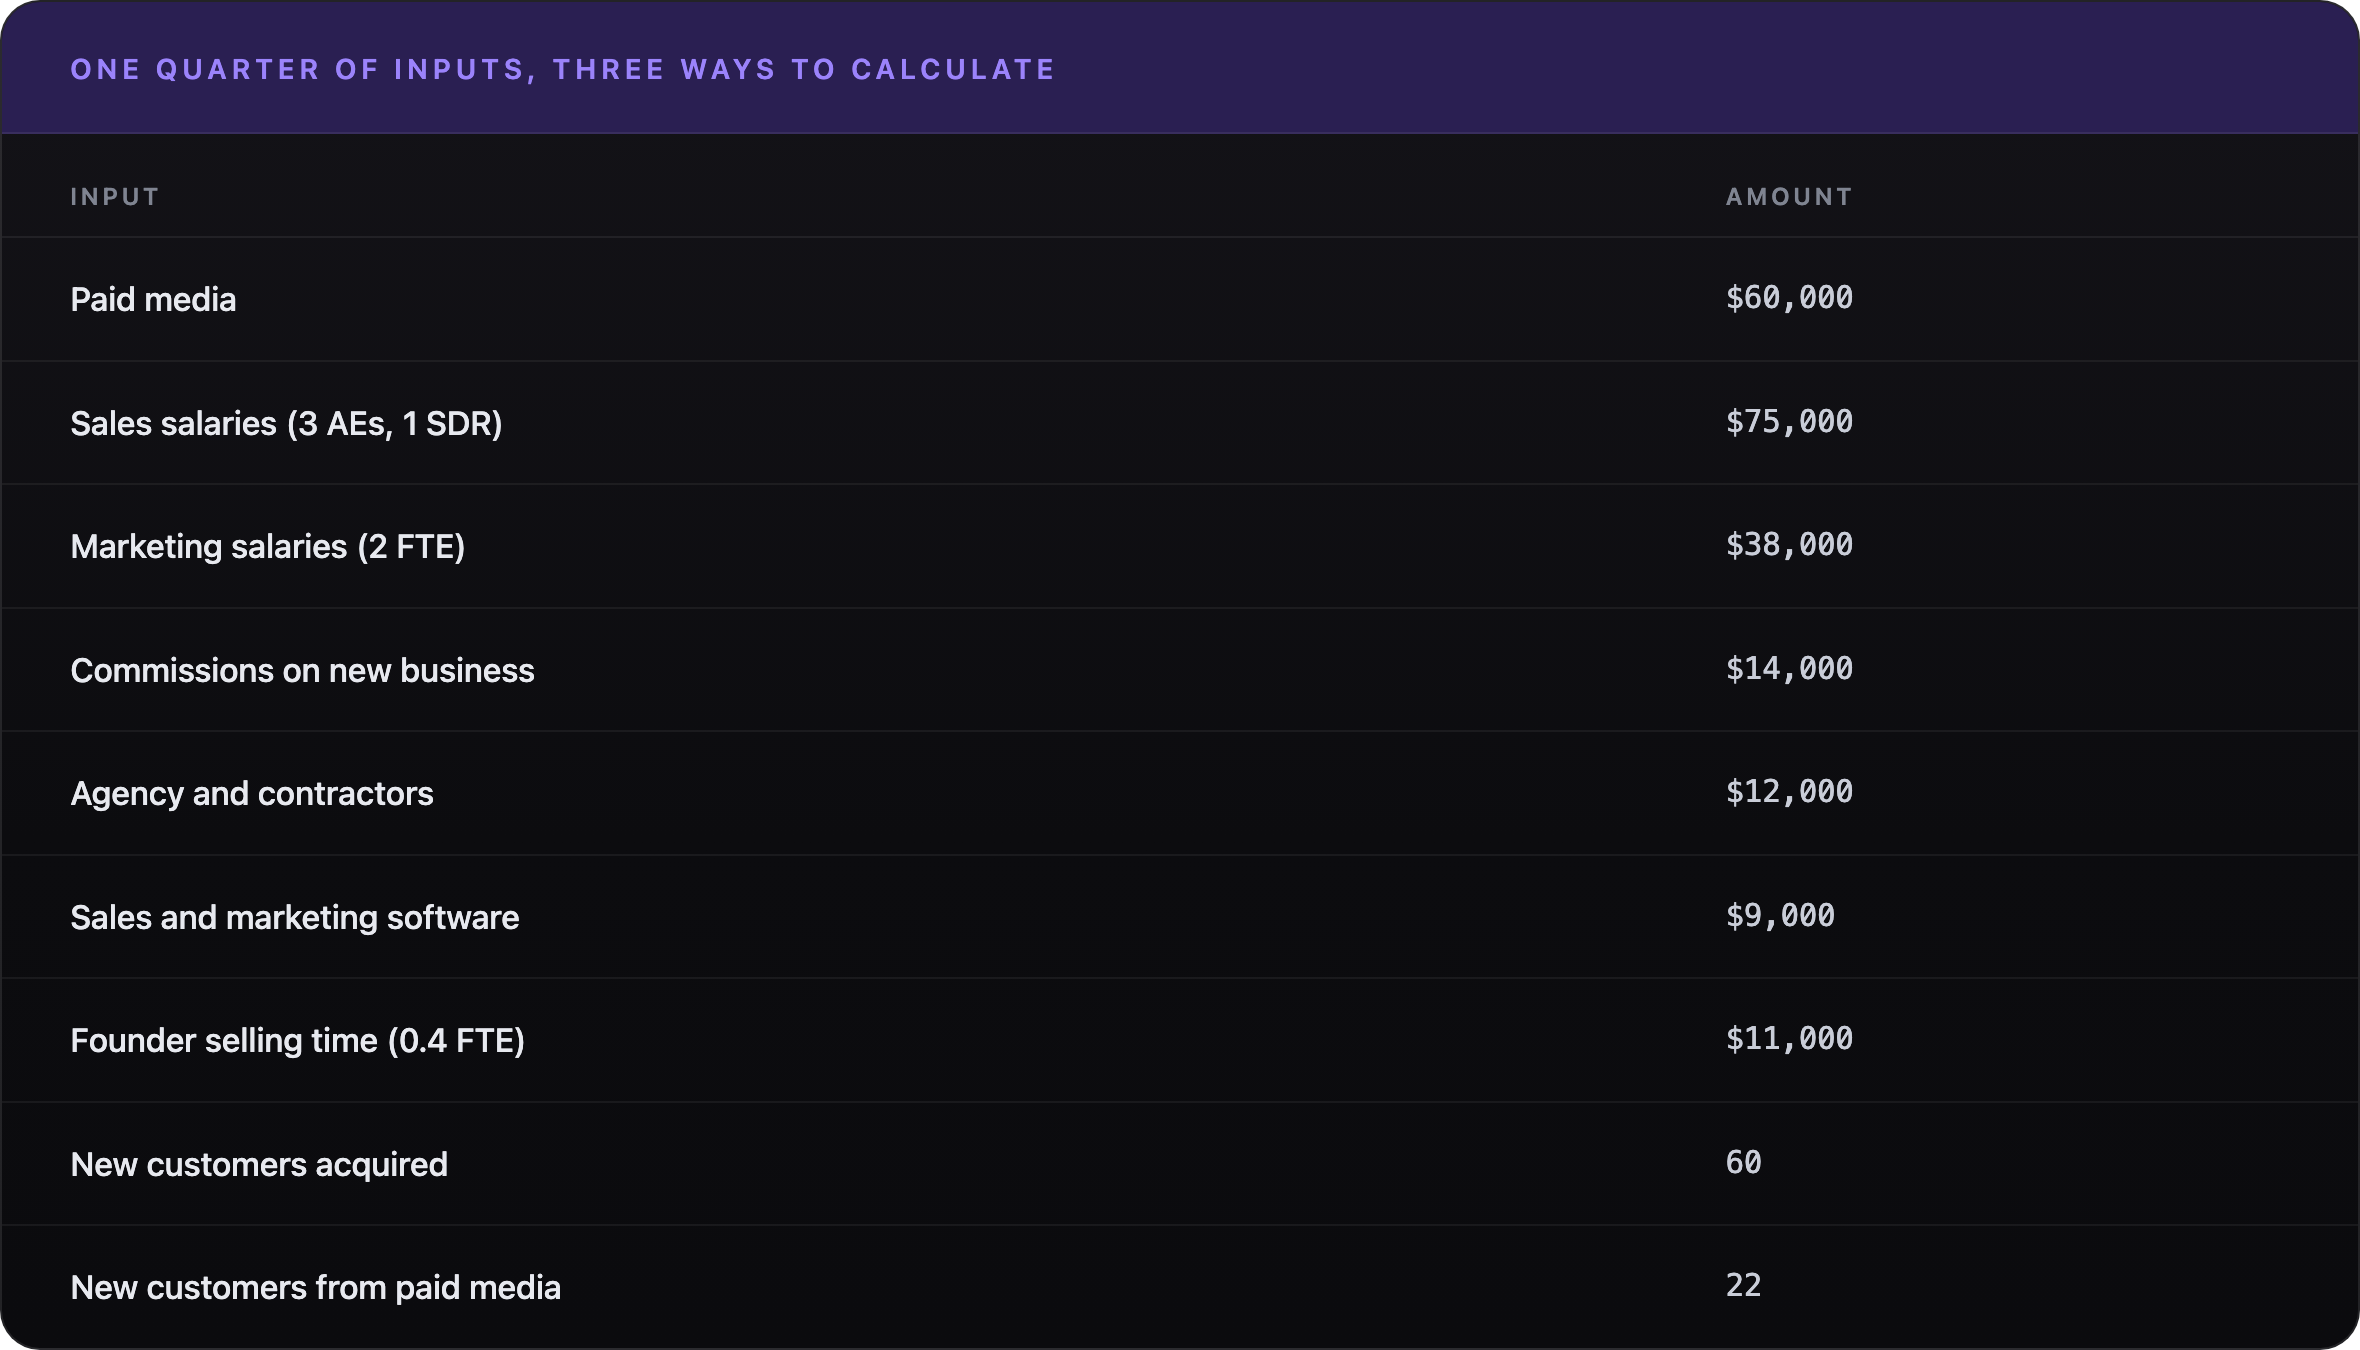
Three calculations follow.
Blended CAC
All acquisition spend, all new customers.
Blended CAC Formula:
Blended CAC = (Paid media + Sales salaries + Marketing salaries + Commissions + Agency and contractors + Software + Founder selling time) ÷ New customers acquired
Belnded CAC Calculation:
(60,000 + 75,000 + 38,000 + 14,000 + 12,000 + 9,000 + 11,000) ÷ 60 = $3,650
Paid CAC
Paid media only, divided by customers attributable to paid.
Paid CAC Formula:
Paid CAC = Paid channel spend ÷ New customers attributable to that channel
Paid CAC Calculation:
60,000 ÷ 22 = $2,727
Fully Loaded CAC
Everything, including the costs most teams leave out. In this example blended and fully loaded are the same figure, because founder time and software are already in. Strip those two out, as many teams do, and you get:
Fully Loaded CAC Formula:
Fully Loaded CAC = (Blended acquisition spend + Costs commonly excluded) ÷ New customers acquired
where commonly excluded = founder and executive selling time, sales and marketing software, onboarding and sales engineering, allocated overhead
Fully Loaded CAC Calculation:
(60,000 + 75,000 + 38,000 + 14,000 + 12,000) ÷ 60 = $3,317
Same quarter. $2,727, $3,317 or $3,650, a spread of a third, depending entirely on which costs were counted.
Which to use:
- Board reporting and fundraising — fully loaded. Anyone doing diligence will rebuild it this way regardless, and a number that moves upward under scrutiny costs you credibility.
- Channel decisions — paid CAC, per channel. Blended tells you nothing about whether to increase a specific budget.
- Trend tracking — pick one and never change it. The direction matters more than the absolute.
What a Good CAC Looks Like, by Motion
There is no absolute benchmark, because CAC scales with contract value. A $3,650 CAC is excellent against a $40,000 annual contract and fatal against a $500 one.
The convention is to judge CAC against what a customer is worth rather than in isolation, using the LTV:CAC ratio. Wall Street Prep's 2024 analysis identifies 3.0x as the standard target — lifetime value at least three times acquisition cost.
Two things that ratio hides.
A ratio above 5:1 is usually read as a triumph. More often it means underinvestment: the business could profitably acquire more customers and isn't. Below 1:1 means each new customer destroys value, and growth makes the problem worse rather than better.
And a healthy ratio says nothing about when the money comes back. Which is the next section.
CAC Payback Period
Payback period is the number of months of gross profit needed to recover the cost of acquiring a customer.
CAC payback (months) = CAC ÷ (Monthly recurring revenue per customer × Gross margin %)
Continuing the example. Sixty customers at $850 MRR each, gross margin 78%:
3,650 ÷ (850 × 0.78) = 3,650 ÷ 663 = 5.5 months
Five and a half months to recover acquisition cost, after which that customer contributes profit. This matters more than the ratio for one reason: LTV is a projection and payback is not.
A 3:1 ratio built on an assumed five-year lifespan is a forecast. Payback is arithmetic on money you have already spent and revenue you are already collecting.
A business with a 4:1 ratio and 26-month payback is financing two years of customer acquisition out of working capital. It can run out of cash while every efficiency metric on the dashboard looks healthy.
Payback periods under roughly 12 months are treated as comfortable for smaller contracts, with 18 to 24 months tolerated in enterprise sales where contracts are longer and stickier — though these are working conventions rather than researched thresholds, and yours should be set against your own runway.
5 Ways CAC Gets Miscalculated
Renewals Counted as New Customers
Inflates the denominator, deflates CAC, and the error grows as the base grows. Count only first-time paying customers.
Sales Salaries Left Out
Usually the largest input. Teams that count only media spend are typically reporting a CAC less than half the real figure.
Self-Serve and Sales-Led Averaged Together
A business with a $200 self-serve motion and a $40,000 enterprise motion has two CACs. The blended figure describes neither and hides that one may be subsidising the other.
Long Cycles Attributed to The Month of Close
A customer who closed in March after a seven-month cycle was acquired with spend from the previous August. Comparing March spend to March closes measures nothing. Either lag the spend or use a window longer than your sales cycle.
Organic Treated as Free
Content, SEO and social have a cost — salaries, tooling, production. Excluding them makes organic look infinitely efficient and distorts every channel comparison built on top.
A Worked Audit: Where The Missing Third Usually Hides
The following is a modeled scenario built from the cost categories above, not a client account. The figures are illustrative.
Take a 40-person B2B SaaS company selling to mid-market, reporting CAC of $1,850 and treating that as healthy against a $28,000 average contract value.
That $1,850 came from dividing paid media by new logos.
Rebuilding it with the inclusion rule from earlier adds four things:
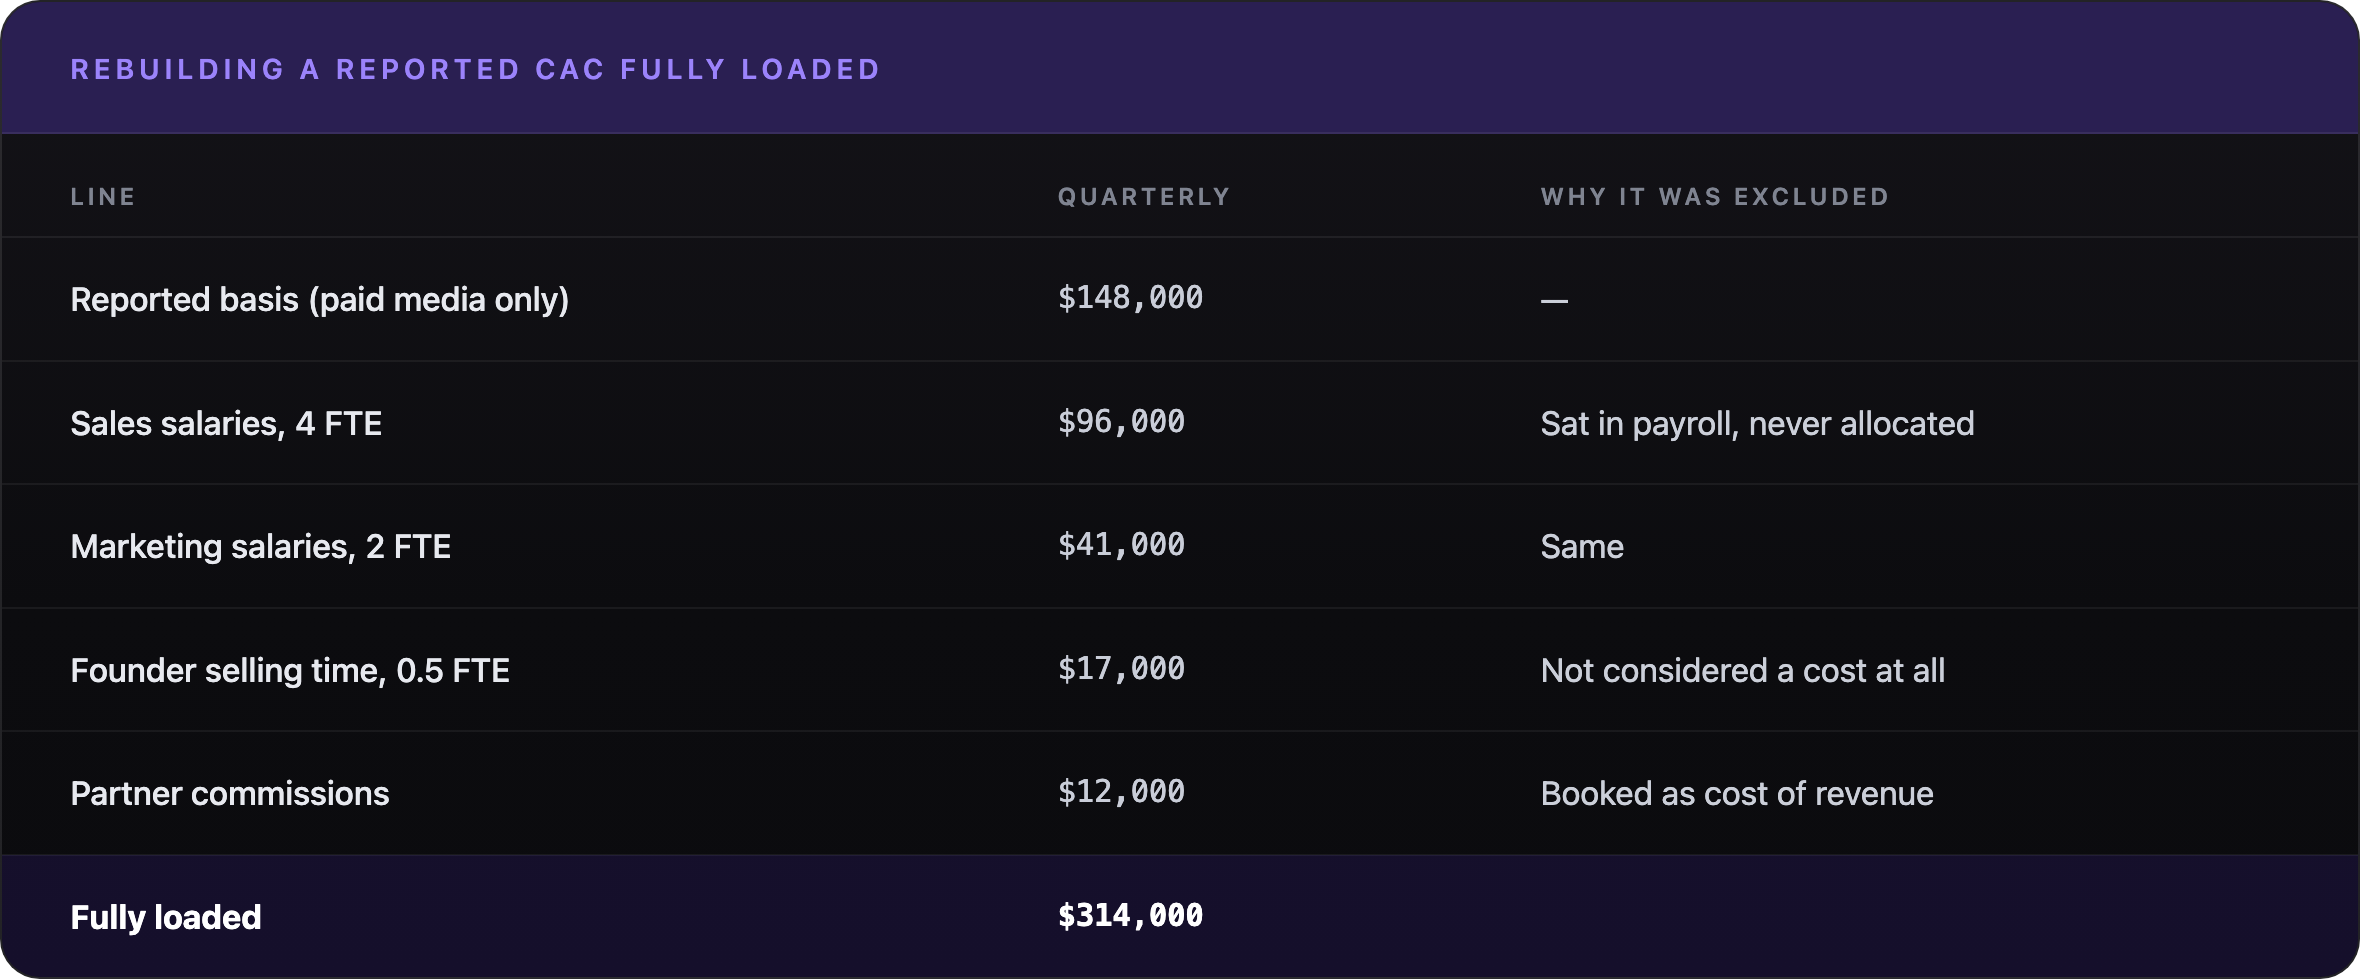
Against 80 new customers, the reported $1,850 becomes $3,925 — slightly more than double.
The LTV:CAC ratio moves with it. At a $28,000 ACV, 76% gross margin and a three-year average life, lifetime value is about $63,800. Against $1,850 that is 34:1, a figure that should have prompted suspicion rather than confidence. Against $3,925 it is 16:1 — still strong, and still suggesting the business is underinvesting in acquisition rather than overspending.
Which is the point. The corrected number did not reveal a problem; it revealed unused headroom. A company that believes its CAC is $1,850 and is nervous about raising it will underspend. One that knows it is $3,925 and that the ratio still clears 15:1 can justify doubling acquisition spend.
The error direction matters here: understating CAC usually reads as good news, which is exactly why it goes unchallenged.
How to Reduce CAC Without Starving Growth
Every lever below buys something and costs something. The trade-off is the point.
Conversion rate before traffic
Doubling landing page conversion halves paid CAC with no extra spend. It is the cheapest lever and the first to check. The cost is engineering and research time that could have gone to product.
Channel Mix
Shifting budget toward lower-CAC channels works until those channels saturate. Watch marginal CAC, not average — the cost of the next customer from a channel, which rises as you scale it. Building a mix that holds up as you scale is its own exercise, covered in how to build a SaaS demand generation strategy.
Sales Cycle Length
Shorter cycles mean each rep closes more, spreading fixed salary cost across more customers. Usually achieved by qualifying harder, which means turning away deals.
Pricing and Packaging
Raising price does not reduce CAC but improves everything CAC is judged against — payback shortens, ratio improves. The cost is conversion rate, and sometimes segment fit.
Retention Feeding Referral
The cheapest customer is one an existing customer brings. This is real but slow, and it is a retention program wearing an acquisition label.
What does not work: cutting acquisition spend to make the number look better. CAC falls, new customers fall faster, and the business shrinks while the dashboard improves.
Turning Customer Acquisition Cost Into a Growth Decision
Recalculate CAC on a fully loaded basis, including sales and marketing salaries, tools, agency costs, and founder selling time. Then split it by acquisition motion or channel instead of relying on one blended figure.
Track the trend as closely as the absolute number. A CAC that rises quarter after quarter can signal declining channel efficiency, tougher competition, or a deteriorating conversion funnel long before the blended figure looks alarming.
If your CAC has never been rebuilt from the ground up, the reported number may understate what acquiring a customer actually costs.
For companies where organic search is a meaningful acquisition channel, apply the same discipline to organic CAC. Account for the full cost of content, SEO, tooling, and internal resources, then compare it with the customers and gross profit the channel produces. That is the approach behind our B2B SaaS SEO work.
FAQs
What is a good customer acquisition cost?
There is no universal figure, because CAC scales with contract value. Judge it against customer lifetime value instead: a ratio of at least 3:1 is the widely used target, per Wall Street Prep's 2024 analysis. A $3,000 CAC is strong against a $40,000 contract and unsustainable against a $500 one.
What is included in customer acquisition cost?
All spend aimed at winning new customers: paid media, sales and marketing salaries, commissions, agencies, software, events, content production, and discounts given to close. Exclude customer success after onboarding, expansion activity, product engineering and general overhead. The test is whether the cost would fall if you stopped acquiring.
What is the difference between CAC and CPA?
Cost per acquisition usually measures the cost of an action — a lead, a signup, a trial. Customer acquisition cost measures the cost of a paying customer. CPA is typically a channel metric, CAC a business one. Confusing them makes acquisition look far cheaper than it is, because most actions never become customers.
What is a good LTV to CAC ratio?
Three to one is the standard target. Below 1:1 each customer destroys value. Above roughly 5:1 usually signals underinvestment rather than excellence — the business could profitably acquire more and isn't. Read the ratio alongside payback period, since a strong ratio built on an optimistic lifespan assumption can still mean a cash problem.
How do you reduce customer acquisition cost?
Improve conversion rate before buying more traffic, since it lowers CAC with no extra spend. Then watch marginal rather than average CAC by channel, shorten the sales cycle by qualifying harder, and review pricing — raising price shortens payback even though it does not lower CAC. Cutting spend outright lowers CAC and growth together.